FD vs. RD: Which Savings Path is Right for You?
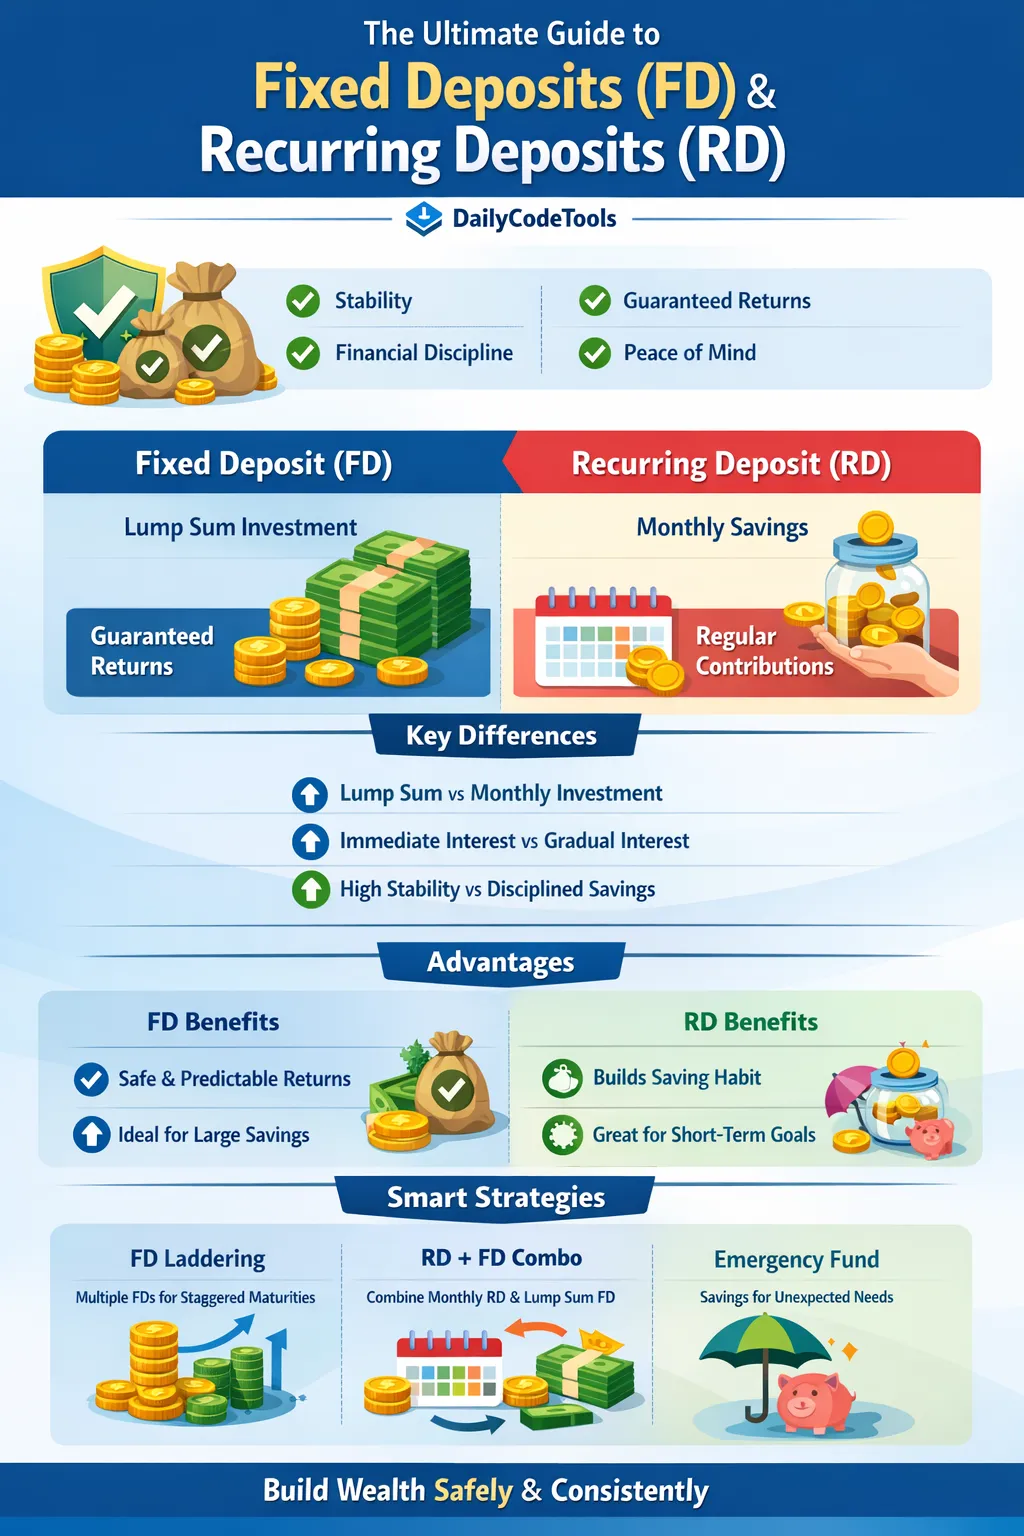
FD vs RD: Fixed Deposit and Recurring Deposit – Complete Guide for Smart Savings
Saving money is one of the most important parts of personal financial planning. Whether you are earning your first salary, running a business, preparing for retirement, or simply trying to build a financial safety net, choosing the right savings instrument can make a meaningful difference over time.
Today, people have access to many financial products, including stocks, mutual funds, bonds, cryptocurrencies, insurance-linked products, and other market-based investments. These options can be useful for different financial goals, but they may also involve varying levels of risk and uncertainty.
For people who prefer predictable returns and structured savings, Fixed Deposits (FDs) and Recurring Deposits (RDs) continue to be popular choices.
A Fixed Deposit is generally designed for people who have a lump sum available for investment. A Recurring Deposit, on the other hand, is designed for people who want to save a fixed amount regularly, usually every month.
Although both products are offered by banks and are generally considered traditional savings instruments, they work differently. Understanding the difference between FD and RD can help you choose an option that matches your income pattern, savings capacity, financial goal, and investment timeline.
In this detailed guide, we will explain:
-
What is a Fixed Deposit?
-
What is a Recurring Deposit?
-
How FD works
-
How RD works
-
FD vs RD differences
-
FD and RD interest calculation
-
Advantages and disadvantages
-
Taxation and TDS considerations
-
Premature withdrawal
-
Loan against FD
-
Goal-based savings
-
Which option is better for different investors
-
Common mistakes to avoid
-
Practical examples
-
Frequently asked questions
By the end of this guide, you should have a clearer understanding of whether an FD or RD is more suitable for your financial situation.
What is a Fixed Deposit?
A Fixed Deposit (FD) is a savings and investment product in which you deposit a lump sum with a bank or eligible financial institution for a predetermined period at an agreed interest rate.
The basic concept is straightforward.
You invest a specific amount for a selected tenure. The deposit earns interest according to the applicable rate and deposit terms. At maturity, you receive the principal along with the interest, subject to the product's conditions and applicable taxes.
For example, suppose you have ₹1,00,000 that you do not immediately need. Instead of keeping the entire amount in a regular savings account, you may consider placing it in an FD for a specified tenure.
The exact maturity amount depends on factors such as:
-
Deposit amount
-
Interest rate
-
Tenure
-
Compounding frequency
-
Payout option
-
Bank or financial institution
-
Applicable tax treatment
One of the biggest attractions of an FD is predictability. Once an FD is booked at a fixed rate, the rate applicable to that deposit generally remains fixed for the agreed tenure, although the exact product conditions should always be checked with the institution.
This makes FDs useful for people who do not want their returns to move up and down with market prices.
How Does a Fixed Deposit Work?
The FD process usually involves a few simple steps.
Step 1: Decide how much you want to invest
You first decide the lump sum amount you can comfortably set aside.
For example:
FD amount = ₹1,00,000
The amount should ideally be money that you do not need for your immediate expenses.
Step 2: Choose the tenure
Banks and financial institutions may offer multiple FD tenures. Depending on the product, these may range from short periods to several years.
Your choice should depend on when you expect to need the money.
For example:
-
Short-term goal → shorter tenure may be suitable
-
Medium-term goal → medium tenure may be considered
-
Long-term capital preservation → longer tenure may be considered
Do not choose a tenure only because it offers a particular interest rate. Your financial goal should also be considered.
Step 3: Check the applicable interest rate
Interest rates can vary between institutions and may differ depending on tenure and customer category.
Some institutions may offer additional interest for eligible senior-citizen deposits, subject to their terms.
Step 4: Select the payout option
Depending on the FD product, you may have options such as receiving interest periodically or allowing it to accumulate until maturity.
If you do not require regular income, a cumulative structure may allow interest to remain invested according to the product's compounding rules.
Step 5: Deposit the money
Once the FD is opened, the bank records the deposit and applies the applicable terms.
Step 6: Receive maturity proceeds
At maturity, the principal and applicable interest are paid according to the selected payout structure.
Key Features of Fixed Deposits
Several characteristics make FDs attractive to conservative savers.
1. Lump-sum investment
FDs generally require an initial deposit of a single amount rather than monthly contributions.
2. Predetermined tenure
You select a tenure when opening the deposit.
3. Fixed interest rate
For a typical fixed-rate FD, the applicable interest rate is locked for that deposit according to the product terms.
4. Predictable maturity
The maturity amount can generally be calculated in advance based on the deposit terms.
5. Multiple tenure options
Different institutions may provide different tenure choices.
6. Digital accessibility
Many banks allow customers to open and manage FDs through internet banking or mobile banking.
7. Premature withdrawal facility
Some FDs may permit premature closure, but conditions, penalties, and reduced interest may apply.
8. Loan or overdraft facility
Certain institutions may provide loans or overdraft facilities against eligible FDs.
Advantages of Fixed Deposits
Capital stability
One of the primary reasons people choose FDs is that they are not directly exposed to daily stock-market fluctuations.
Unlike equity investments, an FD does not normally change in value every day based on market sentiment.
However, it is important not to interpret this as meaning every deposit has zero risk. Deposit protection, institutional strength, and applicable regulations should be considered before investing.
Predictable returns
FDs make financial planning easier because the applicable interest rate and tenure are known at the time of investment.
If you have a known financial requirement in the future, a fixed deposit can help create a predictable pool of money.
Simple to understand
The basic structure is easier to understand than many market-linked investment products.
You deposit money, select a tenure and rate, and receive interest according to the product terms.
Useful for conservative investors
People who prioritize capital stability and predictable returns may find FDs more comfortable than volatile investments.
Suitable for short- and medium-term goals
An FD can be useful when you have a financial goal with a known time horizon and want to avoid exposing that money to market volatility.
Potential access to funds through loan or overdraft
Instead of immediately breaking an FD during an emergency, eligible customers may have the option of borrowing against it, depending on the institution's policy.
This can allow the deposit to continue under its original terms while providing temporary liquidity.
Limitations of Fixed Deposits
FDs are not perfect for every financial goal.
Inflation risk
Inflation reduces purchasing power.
Suppose your deposit earns a nominal return but the cost of goods and services rises significantly during the same period. Your money may increase in rupee terms while its real purchasing power grows much more slowly.
Therefore, investors should consider real returns, not just the stated interest rate.
Limited growth potential
FDs generally provide more predictable returns than market-linked assets, but that predictability may come with lower long-term growth potential compared with investments that carry higher risk.
Premature withdrawal costs
Breaking an FD before maturity may result in a lower effective interest rate or penalty depending on the bank's terms.
Reinvestment risk
Suppose your FD matures and market interest rates have fallen. If you need to reinvest the money, the new FD may offer a lower rate than your previous deposit.
Tax impact
Interest income may be taxable according to applicable tax rules. Therefore, the rate shown by the bank is not necessarily the same as your final post-tax return.
What is a Recurring Deposit?
A Recurring Deposit (RD) is a savings product designed for people who want to invest a fixed amount regularly rather than depositing a large lump sum at the beginning.
The most common structure is a monthly contribution.
For example, instead of investing ₹1,00,000 at once, you might decide to deposit:
₹3,000 every month
for a predetermined period.
This makes an RD particularly useful for salaried employees, freelancers, small-business owners, students, and other people who receive income regularly and want to build savings gradually.
The key idea behind an RD is consistency.
You do not need a large amount of money on day one. Instead, you build the corpus through regular contributions.
How Does a Recurring Deposit Work?
Let's understand the process with a simple example.
Suppose you open an RD with:
-
Monthly deposit: ₹3,000
-
Tenure: 24 months
-
Applicable interest rate: according to the bank's prevailing RD rate
Over 24 months, your total principal contribution would be:
₹3,000 × 24 = ₹72,000
The final maturity amount would be higher than ₹72,000 because of the interest earned, subject to the applicable rate and calculation method.
The important point is that every monthly installment does not remain invested for the same amount of time.
The first installment has the longest period to earn interest.
The second installment has a slightly shorter period.
The final installment has the shortest period.
Therefore, an RD is different from investing the entire amount as an FD on the first day.
Key Features of Recurring Deposits
Regular monthly contributions
The defining feature of an RD is the recurring contribution.
Savings discipline
Because you commit to a fixed installment, an RD can help create a regular savings habit.
Lower starting amount
Many RD products allow customers to start with relatively small monthly amounts, although minimum deposit requirements vary by institution.
Predetermined tenure
You select a tenure according to the product's available options.
Predictable interest structure
The applicable interest rate is determined according to the institution's terms.
Goal-based savings
RDs can be useful for saving toward known short- or medium-term expenses.
Advantages of Recurring Deposits
Easy for salaried individuals
If you receive a salary every month, allocating a fixed amount toward an RD can be easier than arranging a large lump sum.
For example, someone earning ₹40,000 per month may find it easier to save ₹4,000 every month than to invest ₹50,000 at once.
Encourages financial discipline
Automatic monthly savings can reduce the temptation to spend the money.
Useful for short-term goals
An RD can be used for goals such as:
-
Annual insurance premiums
-
Education expenses
-
Travel plans
-
Festival spending
-
Electronics purchases
-
Small business requirements
-
Emergency savings
-
Planned household expenses
Lower market exposure
An RD does not depend on daily stock-market movements.
Simple planning
You know the monthly commitment and the selected tenure in advance.
Limitations of Recurring Deposits
Monthly commitment
Once you start an RD, you need to make regular deposits according to its terms.
Missing installments may result in penalties or other consequences depending on the bank.
Inflation
Just like an FD, an RD may not always generate returns that comfortably exceed inflation.
Taxation
Interest earned on an RD may be taxable according to applicable income-tax rules.
Lower initial compounding than a lump-sum FD
Because the money is deposited gradually, each installment gets a different amount of time to earn interest.
FD vs RD: What is the Difference?
The biggest difference between FD and RD is the investment pattern.
An FD involves investing a lump sum at once.
An RD involves investing a fixed amount at regular intervals.
Here is a simple comparison:
| Feature | Fixed Deposit | Recurring Deposit |
|---|---|---|
| Investment method | Lump sum | Regular installments |
| Suitable for | People with available capital | People with regular income |
| Contribution | Usually one-time | Usually monthly |
| Savings discipline | Moderate | High |
| Interest calculation | Based on deposit and terms | Based on installments and terms |
| Liquidity | Depends on product | Depends on product |
| Premature closure | Conditions may apply | Conditions may apply |
| Market exposure | Generally none | Generally none |
| Tax on interest | Applicable as per rules | Applicable as per rules |
| Best suited for | Lump-sum savings | Goal-based monthly savings |
The table makes the basic difference clear, but choosing between the two requires looking at your personal financial situation.
FD or RD: Which One is Better?
There is no universal answer.
The better option depends on how you receive and manage your money.
Choose FD when you have a lump sum
Suppose you receive:
-
A yearly bonus
-
An inheritance
-
Proceeds from selling an asset
-
A matured investment
-
Excess savings
If you do not need the money immediately, an FD may be considered.
Choose RD when you earn regularly
If your income comes monthly and you do not currently have a large amount available, RD can help you save systematically.
Example
Imagine two people.
Person A has ₹2,00,000 sitting in a bank account and wants to keep it aside for a future goal.
An FD may be more appropriate to evaluate because the entire amount is available today.
Person B can save ₹8,000 every month but does not have ₹2,00,000 available.
An RD may fit Person B's savings pattern better.
FD vs RD Interest Calculation
Understanding how interest works is important before investing.
FD calculation
For a cumulative FD, the maturity amount depends on the principal, interest rate, tenure, and compounding frequency.
A simplified compound-interest concept can be represented as:
A = P(1 + r/n)^(nt)
Where:
-
A = maturity amount
-
P = principal
-
r = annual interest rate
-
n = number of compounding periods per year
-
t = time in years
The actual calculation method can vary depending on the deposit product and institution.
Therefore, the bank's official maturity calculation should be used for the exact figure.
RD calculation
RD calculation is different because each installment is invested at a different point in time.
For example, if you deposit ₹5,000 every month for 12 months, the first installment remains invested longer than the last installment.
This is why you should not simply apply the FD formula to the total RD contribution.
Online calculators provided by banks can be useful for estimating maturity amounts, but always verify the final amount and terms with the financial institution.
Example: How an FD Can Help with a Future Goal
Suppose you have ₹2,00,000 today and want to use it after three years for a planned expense.
Instead of leaving all the money idle, you could compare available FD options and select a suitable tenure and interest rate.
The benefit is not necessarily maximum possible growth.
The primary benefit is predictability.
You can estimate the maturity amount and align the deposit with your expected financial requirement.
However, before opening the FD, consider whether you may need the money earlier. If early withdrawal is likely, locking the entire amount into a long tenure may not be appropriate.
Example: How an RD Can Build a Corpus
Suppose your monthly income allows you to save ₹5,000.
You decide to put ₹5,000 into an RD every month for 24 months.
Your total contribution would be:
₹5,000 × 24 = ₹1,20,000
The maturity value will be higher than your total contribution because of the interest earned, subject to the applicable rate and terms.
This demonstrates the main advantage of an RD: you can create a meaningful corpus without having the entire investment amount available at the beginning.
FD and RD for Emergency Funds
Emergency funds are designed to cover unexpected expenses such as:
-
Temporary loss of income
-
Urgent household expenses
-
Essential repairs
-
Unexpected travel
-
Other financial emergencies
Liquidity is extremely important for emergency savings.
For this reason, you should not automatically lock your entire emergency fund into a long-term FD or RD.
A practical approach may be to keep an immediately accessible portion in a suitable liquid savings arrangement and consider deposits for money that is not required immediately.
Before using an FD as part of an emergency strategy, check premature-withdrawal rules and the actual access process.
FD and RD for Short-Term Financial Goals
Short-term financial goals are often easier to plan when the amount and deadline are known.
For example:
Goal: ₹1,20,000 in 24 months.
If you already have a large amount available, an FD may be worth considering.
If you need to build the amount from monthly income, an RD may be more natural.
This goal-based approach is more useful than asking whether FD is always better than RD.
The right question is:
"How much money do I have today, how much can I save regularly, and when will I need the money?"
FD and RD for Retirement Planning
FDs and RDs can play a role in conservative financial planning, but they should not automatically be treated as complete retirement strategies.
Retirement planning usually involves considering:
-
Current income
-
Expected expenses
-
Inflation
-
Retirement age
-
Longevity
-
Healthcare costs
-
Taxation
-
Other investments
-
Required retirement corpus
An FD may be useful for preserving a portion of retirement savings or generating predictable income, depending on the individual's overall strategy.
An RD may be useful during the accumulation phase when someone is gradually building savings.
However, retirement planning should generally consider the impact of inflation over a long period.
FD Laddering Strategy
One useful strategy for managing FDs is FD laddering.
Instead of investing all your money into a single FD with the same maturity date, you can divide the amount into multiple deposits with different maturity dates.
For example, suppose you have ₹4,00,000.
Instead of one ₹4,00,000 FD, you could potentially divide it into four ₹1,00,000 deposits with different maturity schedules, subject to available products and your financial goals.
The potential benefits include:
-
More frequent liquidity
-
Easier access to money
-
Reduced dependence on one maturity date
-
Ability to reinvest portions at different interest rates
Laddering does not eliminate interest-rate or inflation risk, but it can improve liquidity management.
Should You Break an FD Before Maturity?
Sometimes an emergency makes premature withdrawal necessary.
Before breaking an FD, check:
-
Whether premature withdrawal is permitted
-
What penalty applies
-
What interest rate will ultimately be paid
-
Whether an alternative such as a loan/overdraft against the deposit is available
-
Whether another source of liquidity is cheaper
If the bank offers a loan or overdraft against the FD on suitable terms, that option may sometimes be worth comparing with premature closure.
The best choice depends on the cost of borrowing and the consequences of breaking the deposit.
Loan Against FD
Some financial institutions offer loans or overdrafts against eligible fixed deposits.
The basic idea is simple.
Instead of withdrawing your FD, you use it as security for borrowing.
Potential advantages can include:
-
Access to funds without immediately closing the deposit
-
Deposit may continue according to its terms
-
Useful for temporary liquidity needs
However, a loan is still a liability.
Before using this facility, compare:
-
Interest charged on the loan
-
Interest earned on the FD
-
Processing charges
-
Repayment terms
-
Consequences of default
Never assume that a loan against FD is automatically cheaper or better.
FD and RD Taxation
Interest earned from bank deposits can have tax implications.
Interest income is generally considered taxable income under the applicable tax rules and may need to be reported in your income-tax return.
Banks may also deduct Tax Deducted at Source (TDS) when the applicable conditions and thresholds are met.
The important point is:
No TDS does not necessarily mean no tax liability.
TDS and final tax liability are different concepts.
Your actual tax liability depends on your overall taxable income, applicable tax regime, exemptions/deductions where available, and prevailing tax rules.
Because tax rules can change, always check the latest Income Tax Department guidance or consult a qualified tax professional for your specific situation.
What are Form 15G and 15H?
Eligible taxpayers may be able to submit forms such as 15G or 15H to request non-deduction of TDS when the prescribed conditions are satisfied.
These forms are not universal exemptions from tax.
Eligibility depends on factors such as age, income, tax liability, and the applicable rules for the relevant financial year.
Therefore, do not submit these forms simply because you want to avoid TDS. First confirm that you meet all applicable conditions.
Senior Citizens and FD
Fixed deposits are often considered by senior citizens because predictable interest income can be useful for financial planning.
Some banks provide additional interest rates to eligible senior citizens, subject to their own terms.
However, senior citizens should consider more than just the advertised interest rate.
Important factors include:
-
Safety of the institution
-
Deposit insurance coverage where applicable
-
Liquidity
-
Tax treatment
-
Interest payout frequency
-
Premature withdrawal rules
-
Nomination
-
Estate planning
-
Overall retirement income needs
A slightly higher rate is not necessarily worth accepting significantly higher risk or reduced liquidity.
Common Mistakes While Investing in FD and RD
Mistake 1: Choosing only the highest interest rate
A high rate may look attractive, but the institution's credibility, deposit protection, liquidity, tenure and conditions should also be considered.
Mistake 2: Ignoring inflation
A 7% nominal return does not mean your purchasing power increases by 7%.
Always think about the difference between nominal return and real return.
Mistake 3: Locking emergency money
Money that may be needed tomorrow should not automatically be locked away for several years.
Mistake 4: Ignoring tax
Compare returns after considering applicable taxes rather than looking only at the advertised interest rate.
Mistake 5: Not checking premature closure rules
Before opening a long-term deposit, understand what happens if you need the money early.
Mistake 6: Putting all money into one deposit
Concentration can create liquidity and reinvestment problems.
Depending on the situation, splitting deposits can provide more flexibility.
Mistake 7: Forgetting maturity instructions
Always check what happens when your FD matures.
Some deposits may be renewed according to selected instructions, while others may transfer proceeds differently.
Mistake 8: Not updating nominee details
Nomination can simplify the process of dealing with deposit proceeds in the event of the depositor's death.
Keep nomination and account information updated according to your circumstances.
How to Choose Between FD and RD
Use the following decision framework.
Choose FD if:
-
You already have a lump sum
-
You want predictable returns
-
You have a known future requirement
-
You do not need the money immediately
-
You prefer a simple investment structure
-
You want to reduce exposure to market volatility
Consider RD if:
-
You earn a regular monthly income
-
You do not have a large lump sum
-
You want to develop a savings habit
-
You have a specific short- or medium-term goal
-
You prefer automatic monthly saving
Consider using both if:
-
You already have some savings
-
You also have regular monthly income
-
You have multiple financial goals
-
You want both lump-sum deployment and systematic savings
Using both products does not automatically make a portfolio better. The combination should be based on your cash flow and financial objectives.
FD vs RD: A Simple Decision Example
Imagine you have ₹3,00,000 in savings.
You also earn ₹50,000 every month and can save another ₹5,000 monthly.
Instead of asking "FD or RD?" you could divide the decision into two parts.
Existing ₹3,00,000
You could evaluate suitable FD options for the lump sum, while keeping enough money accessible for emergencies.
Monthly ₹5,000
You could evaluate an RD for systematic savings.
This approach matches each product to the type of money you actually have.
The FD handles the existing lump sum.
The RD handles the future monthly savings.
FD vs RD: Which Gives Higher Returns?
This question requires careful consideration.
An FD and RD with the same advertised annual interest rate do not necessarily produce the same maturity value on the same total amount contributed, because the timing of investment is different.
In an FD, the entire principal is invested from the beginning.
In an RD, money enters the account gradually.
Therefore, the first FD rupee may earn interest for the entire investment period, whereas the final RD installment has much less time to earn interest.
However, comparing "returns" without considering the investment amount, cash-flow pattern, tenure, taxation, and liquidity can be misleading.
The better product is the one that fits your actual financial situation.
FD vs RD vs Savings Account
These products serve different purposes.
Savings account
Best suited for:
-
Day-to-day transactions
-
Immediate liquidity
-
Regular expenses
-
Emergency access
FD
Best suited for:
-
Lump-sum savings
-
Predictable returns
-
Money that may not be required immediately
RD
Best suited for:
-
Regular monthly saving
-
Goal-based accumulation
-
Building financial discipline
A financially organized person may use all three for different purposes.
For example:
Savings account → daily expenses
FD → existing surplus
RD → monthly goal-based savings
How to Maximize the Usefulness of FD and RD
Set a clear goal
Do not invest blindly.
Ask:
Why am I saving this money?
A goal gives you a target amount and timeline.
Match the tenure with the goal
If you need money in 18 months, do not automatically choose a five-year product simply because the rate looks attractive.
Compare institutions
Before opening a deposit, compare:
-
Interest rate
-
Tenure
-
Premature withdrawal terms
-
Minimum deposit
-
Senior-citizen benefits
-
Payout options
-
Digital service
-
Deposit protection and applicable regulatory framework
Consider post-tax returns
The headline rate is not always your final return.
Keep liquidity in mind
Do not lock every rupee.
Review periodically
Your income, expenses, goals and interest-rate environment can change.
A deposit strategy that made sense two years ago may not be ideal today.
FD and RD: Safety Considerations
People often describe FD and RD as "100% safe."
That statement is too broad.
The safety of a bank deposit depends on factors including the institution, regulatory framework and applicable deposit-insurance provisions.
Therefore, investors should understand the relevant deposit insurance limit and conditions applicable in their jurisdiction rather than assuming every deposit amount is fully protected.
If you are considering a deposit with a bank or financial institution, review the institution's official terms and applicable regulatory information.
Safety should always be evaluated alongside returns.
Why Inflation Matters for FD and RD
Suppose you save ₹1,00,000 today.
After several years, the number in your account may be higher.
But what matters is what that money can actually buy.
If prices rise significantly during the same period, the purchasing power of your savings may not increase as much as the account balance suggests.
This is known as inflation risk.
For this reason, FD and RD can be excellent tools for stability and planned savings, but they may not be the only instruments required for long-term wealth creation.
A balanced financial plan should consider:
-
Safety
-
Liquidity
-
Inflation
-
Tax
-
Growth
-
Time horizon
-
Risk tolerance
FD and RD for Different Age Groups
Young professionals
A young professional may use an RD to establish a savings habit while maintaining an emergency fund.
As income increases, surplus savings may be allocated across different investments based on goals and risk tolerance.
Families
Families may use FDs for planned expenses and RDs for upcoming purchases or annual financial commitments.
Business owners
Business owners may prefer liquidity because cash-flow requirements can change. Deposits should therefore be structured carefully rather than locking all available cash.
Retirees
Retirees may prioritize capital stability and predictable income, making deposits relevant to their financial planning. Tax, inflation, liquidity and overall retirement income should still be considered.
Frequently Asked Questions About FD and RD
Is FD better than RD?
Not necessarily.
FD is generally more suitable when you already have a lump sum, while RD is generally more suitable when you want to save a fixed amount regularly.
The better option depends on your financial situation.
Can I open an FD and RD together?
Yes, if the respective institution offers both products and you meet their eligibility requirements.
Using both can be useful when you have both existing savings and regular monthly savings.
Is RD completely risk-free?
RDs are generally considered low-risk compared with market-linked investments, but "risk-free" should not be interpreted as a guarantee under every circumstance. Consider the institution, applicable deposit protection and product terms.
Is FD interest taxable?
Interest income from an FD can be taxable according to applicable income-tax rules.
Is RD interest taxable?
RD interest can also have tax implications. The exact treatment depends on the prevailing tax rules and your individual circumstances.
Can I withdraw FD before maturity?
Many FD products allow premature withdrawal subject to conditions. Penalties or reduced interest may apply.
Can I miss an RD installment?
The consequences of a missed installment depend on the bank's RD terms. Penalties or other account consequences may apply.
Which is better for monthly income?
An FD with an appropriate interest-payout structure may be more suitable for someone who already has a lump sum and wants periodic interest income. An RD is primarily designed for systematic accumulation rather than immediate income generation.
Which is better for saving a small amount every month?
An RD may be more naturally suited to this situation because it is designed around recurring contributions.
Can I take a loan against an FD?
Some institutions offer loans or overdrafts against eligible FDs. Check the specific product terms before relying on this facility.
Does a higher FD interest rate always mean a better FD?
No.
You should also consider institution quality, deposit protection, tenure, liquidity, premature withdrawal rules, tax and your financial goal.
How much should I invest in an FD?
There is no universal amount.
The amount should depend on your emergency fund, financial goals, available surplus, risk tolerance and overall investment plan.
How much should I put into an RD every month?
Choose an amount that you can comfortably maintain without affecting essential expenses.
Consistency is more important than selecting an unnecessarily large monthly installment.
Final Thoughts: FD vs RD
Fixed Deposits and Recurring Deposits are simple financial products, but their simplicity is exactly what makes them useful for many savers.
An FD is built around a lump-sum investment.
An RD is built around regular savings.
Neither product is automatically better for everyone.
If you already have a significant amount of money available and want a predictable savings structure, an FD may be worth considering.
If you earn regularly and want to save a fixed amount every month, an RD may be more suitable.
For many people, the most practical approach is not choosing one product exclusively. Instead, different savings instruments can be assigned different jobs.
For example:
-
Keep readily required money accessible.
-
Use an FD for suitable lump-sum savings.
-
Use an RD for regular goal-based contributions.
-
Consider inflation and taxes when evaluating returns.
-
Avoid locking emergency money unnecessarily.
-
Compare institutions and product terms before investing.
-
Review your savings strategy as your income and goals change.
The most important principle is not to chase the highest advertised interest rate blindly.
Good financial planning is about matching the right product with the right goal, time horizon, liquidity requirement and level of risk.
FDs and RDs may not provide overnight wealth, but they can help create financial discipline, predictable savings and a stronger foundation for future financial decisions.
Before investing, always check the latest interest rates, terms, taxation rules, premature withdrawal conditions and applicable deposit-protection provisions directly with the relevant financial institution and official regulatory sources.
Disclaimer: This article is for general educational and informational purposes only. It should not be treated as personalized financial, tax or investment advice. Financial products, interest rates, taxation rules and regulatory provisions may change over time. Verify the latest applicable information before making an investment decision.
Your email address will not be published. Comments are moderated.
0 Comments on This Post
Leave a Reply
Comments (0)
Spread the Word!
Join Our Developer Community!
Get weekly coding tips, tool updates, and exclusive tutorials straight to your inbox.
Request a Tool
×