How to Pay Off Credit Card Debt Faster
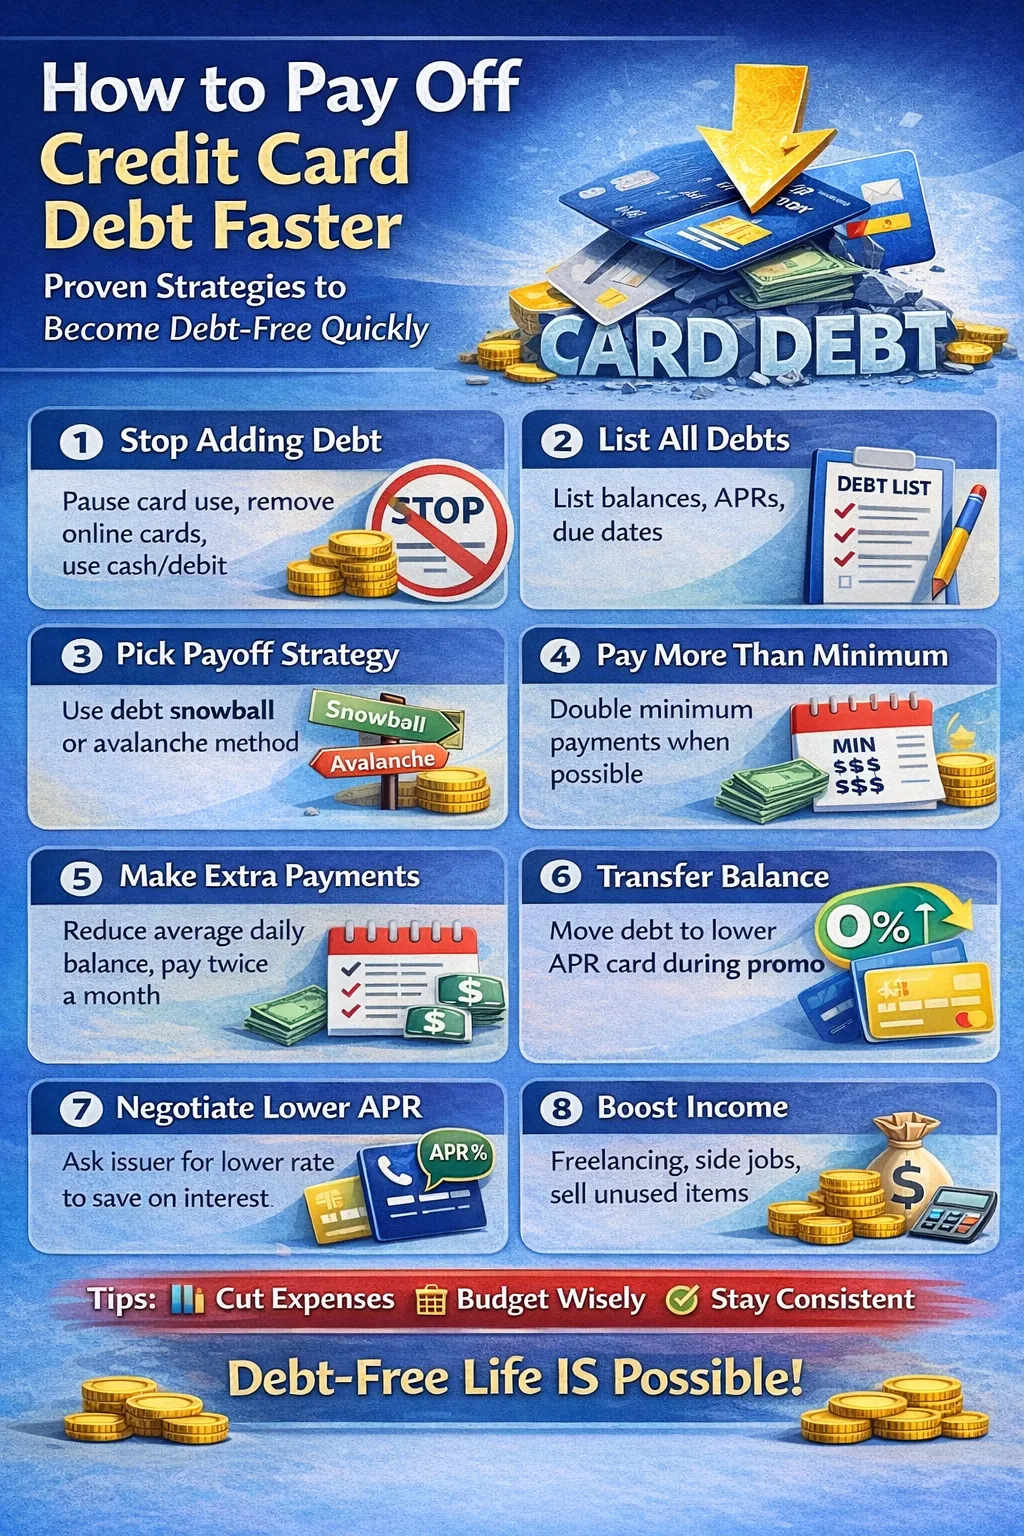
Credit card debt is one of the most common financial challenges faced by consumers around the world.
Credit cards can be useful financial tools. They can help you manage short-term expenses, build a credit history, earn rewards, pay for emergencies, and make online purchases convenient.
But credit cards can also become expensive when a balance is carried from one billing cycle to the next.
High interest rates, minimum payments, late fees, impulse spending, and multiple balances can make debt feel difficult to escape. What starts as a small purchase can eventually become a large balance that takes months or years to repay.
If you are currently carrying credit card debt, you are not alone. More importantly, credit card debt can be managed and eliminated with a realistic strategy.
The key is to understand exactly how your debt works, stop adding unnecessary balances, choose an appropriate repayment method, and consistently direct as much money as reasonably possible toward your debt.
This complete guide explains how to pay off credit card debt faster without relying on unrealistic promises.
You will learn:
-
Why credit card debt becomes expensive
-
How APR and interest charges work
-
Why minimum payments can slow repayment
-
How to calculate your total debt
-
How to create a debt payoff plan
-
Debt snowball vs. debt avalanche
-
How to choose the right strategy
-
Why paying more than the minimum matters
-
Whether multiple monthly payments can help
-
How balance transfers work
-
When a lower-interest consolidation loan may make sense
-
How to negotiate a lower APR
-
How to reduce expenses
-
How to increase income
-
How to create a debt-focused budget
-
How to build an emergency fund while paying debt
-
How credit utilization can affect your credit profile
-
What to do when debt feels overwhelming
-
How credit counseling and debt management plans work
-
What to know about debt settlement
-
Common mistakes to avoid
-
Psychological strategies for staying motivated
-
How to prevent credit card debt from returning
-
A practical step-by-step debt payoff plan
-
Frequently asked questions
By the end of this guide, you should have a practical roadmap for reducing credit card debt and moving toward greater financial stability.
Important: This article provides general educational information, not personalized financial, legal, tax, or debt-relief advice. Interest rates, consumer protections, fees, and credit-card rules vary by country, card issuer, and individual circumstances.
Why Does Credit Card Debt Grow So Fast?
The biggest reason credit card debt can become expensive is interest.
Credit cards often have much higher interest rates than secured loans such as mortgages. Depending on the country, card, issuer, and borrower, an annual percentage rate (APR) can be relatively high.
For example, imagine you have a credit card balance of:
$5,000
and the card has an APR of:
24%
A simplified annual-interest calculation would be:
$5,000 × 24% = $1,200
That does not mean exactly $1,200 will be added to your account every year because actual credit-card interest calculations depend on the issuer's terms, daily balances, payment timing, grace periods, and other factors.
But the example demonstrates an important principle:
A high interest rate can make carrying a balance very expensive.
The longer you carry the balance, the more opportunity there is for interest charges to accumulate.
What Is APR on a Credit Card?
APR stands for Annual Percentage Rate.
It represents the annualized cost of borrowing, expressed as a percentage, subject to the terms of the credit agreement.
For example:
-
10% APR
-
18% APR
-
24% APR
-
29% APR
The higher the APR, generally, the more expensive it is to carry a balance.
However, APR alone doesn't tell you exactly how much interest you'll pay in a particular billing cycle.
Credit-card issuers may calculate interest using a daily periodic rate and a method based on daily balances or average daily balances, depending on the account terms.
That is why two people with the same starting balance can sometimes pay different amounts of interest depending on:
-
Payment dates
-
New purchases
-
Existing balances
-
Promotional rates
-
Grace periods
-
Fees
-
Card terms
Understanding your specific card agreement is important.
Why Minimum Payments Can Keep You in Debt Longer
Every credit card statement typically includes a minimum payment.
Paying at least the required minimum generally helps you avoid being considered late, assuming you pay by the due date.
But making only minimum payments can result in a long repayment period.
For example, imagine you have a balance of $8,000 and a relatively high APR.
If you make only small minimum payments, a significant portion of each payment may go toward interest and other charges rather than reducing the principal balance quickly.
This creates a frustrating cycle:
Large balance → interest charges → small principal reduction → large balance
The exact payoff period depends on the card's APR, minimum-payment formula, fees, and whether you continue making new purchases.
The important lesson is:
Paying the minimum may keep the account current, but paying more than the minimum can help reduce the balance much faster.
Step 1: Stop Adding New Credit Card Debt
Before trying to eliminate your existing balance, address the first problem:
Are you still adding new debt?
If your balance is increasing every month, making larger payments may not be enough to create meaningful progress.
For example:
-
Existing balance: $5,000
-
New monthly purchases: $700
-
Monthly payment: $600
Even though you are making payments, your overall balance may not fall as quickly as you expect.
You need to create a gap between:
What you spend
and
What you repay.
Depending on your circumstances, consider temporarily:
-
Stopping unnecessary credit-card purchases
-
Removing saved cards from shopping websites
-
Using debit or cash for everyday purchases
-
Taking a break from discretionary spending
-
Keeping one card available for genuine emergencies if appropriate
-
Creating a weekly spending limit
You do not necessarily need to permanently stop using every credit card.
The goal is to stop using credit to finance spending that you cannot currently afford to repay.
Step 2: Make a Complete List of Your Debts
You cannot create an effective payoff strategy without knowing what you owe.
Create a list of every credit card.
Record:
| Card | Balance | APR | Minimum Payment | Due Date |
|---|---|---|---|---|
| Card A | $3,500 | 25% | $100 | 10th |
| Card B | $2,000 | 19% | $60 | 15th |
| Card C | $1,500 | 28% | $50 | 22nd |
Your exact numbers will be different.
The purpose of the table is simply to create visibility.
Calculate:
Total balance
Add every outstanding balance.
Total minimum payments
Add the required minimum payment for every account.
Highest APR
Identify the card charging the highest interest rate.
Lowest balance
Identify the account with the smallest balance.
This information will help you choose between different payoff methods.
Step 3: Understand Your Cash Flow
Before deciding how much extra to put toward debt, determine how much money is actually available.
Start with your monthly income.
Then subtract essential expenses such as:
-
Housing
-
Utilities
-
Groceries
-
Transportation
-
Insurance
-
Healthcare
-
Childcare
-
Minimum debt payments
-
Essential subscriptions or services
Then look at discretionary expenses.
Examples include:
-
Restaurants
-
Entertainment
-
Shopping
-
Travel
-
Streaming services
-
Hobbies
-
Takeout
-
Unplanned purchases
The amount left after essential expenses tells you how much flexibility you have.
You might discover that you can redirect:
-
$100 per month
-
$250 per month
-
$500 per month
-
$1,000 per month
toward debt.
The important thing is to choose an amount that is aggressive but sustainable.
A plan that works for three months and then collapses is less useful than a realistic plan you can maintain for a year.
Step 4: Choose a Debt Repayment Strategy
Two of the most popular strategies are:
-
Debt Snowball
-
Debt Avalanche
Both can work.
The difference is how you choose which debt receives your extra payment.
What Is the Debt Snowball Method?
The debt snowball method focuses on paying off your smallest balance first, regardless of its interest rate.
For example:
-
Card A: $500 at 28%
-
Card B: $2,000 at 20%
-
Card C: $5,000 at 24%
Under the snowball method, you focus on:
Card A → Card B → Card C
You continue making the minimum payment on the other cards while putting extra money toward the smallest balance.
Once Card A is completely paid off, you redirect the money that had been going toward Card A to Card B.
Then you repeat the process.
Why Does the Snowball Method Work?
The snowball method is primarily powerful because of behavioral psychology.
Paying off a $500 balance can feel much more achievable than looking at a $10,000 total debt.
After you eliminate the first account, you get a visible win.
That can create momentum.
For some people, motivation is more important than mathematical optimization.
If you are someone who gets discouraged easily, seeing individual accounts disappear can make it easier to stay committed.
Debt Snowball Example
Imagine you have:
-
Card A: $600
-
Card B: $2,500
-
Card C: $6,000
You continue paying the required minimums on all three.
Then you put your additional debt-payoff money toward Card A.
Once Card A reaches $0, you take the amount previously allocated to Card A and add it to your payment for Card B.
Eventually:
Card A → $0
Then:
Card B → $0
Then:
Card C → $0
This creates the "snowball" effect.
What Is the Debt Avalanche Method?
The debt avalanche method focuses on the debt with the highest interest rate.
For example:
-
Card A: $600 at 28%
-
Card B: $2,500 at 20%
-
Card C: $6,000 at 24%
The avalanche order would be:
Card A → Card C → Card B
because Card A has the highest APR, followed by Card C, then Card B.
You continue making minimum payments on all accounts while directing your extra money toward the highest-interest debt.
After that debt is eliminated, you move to the next-highest APR.
Why Is the Debt Avalanche Mathematically Efficient?
The avalanche method attacks the debt that is costing you the most in interest.
Suppose:
-
Card A = $3,000 at 29%
-
Card B = $3,000 at 15%
If both balances are the same size, Card A is costing considerably more in interest.
Putting extra money toward the 29% balance can reduce the amount of high-rate debt faster.
Assuming all other factors remain the same, the avalanche method generally minimizes total interest compared with paying a lower-rate debt first.
This is why it is often considered the mathematically optimal approach for paying down multiple high-interest debts.
Debt Snowball vs Debt Avalanche
| Feature | Snowball | Avalanche |
|---|---|---|
| First target | Smallest balance | Highest APR |
| Main advantage | Motivation | Interest savings |
| Quick wins | Usually stronger | May take longer initially |
| Mathematical efficiency | Not always optimal | Usually optimal |
| Best for | People motivated by progress | People focused on minimizing interest |
So which one should you use?
Choose Snowball if:
-
You need quick psychological wins.
-
You struggle to stay motivated.
-
You want to eliminate accounts quickly.
-
Seeing fewer bills motivates you.
Choose Avalanche if:
-
You want to minimize interest.
-
You are comfortable waiting longer for the first payoff.
-
You prefer a mathematical approach.
-
Your highest-APR balance is large.
The most important strategy is the one you can actually follow consistently.
Step 5: Pay More Than the Minimum
One of the simplest ways to accelerate debt payoff is to increase your monthly payment.
Suppose your minimum payment is:
$75
and you can afford:
$200
Paying an extra $125 each month can make a significant difference over time.
If you can afford $300 instead of $200, the payoff can accelerate further.
There is no universal "perfect" extra payment.
Your goal is to identify the largest sustainable amount that fits your budget.
What If You Can Only Afford the Minimum?
Do not assume that you are failing.
If the minimum is genuinely all you can afford right now, prioritize making required payments on time while looking for ways to improve your situation.
You can explore:
-
Expense reductions
-
Additional income
-
Lower-interest options
-
Credit counseling
-
A hardship program from your issuer
-
A debt management plan if appropriate
The first goal is to prevent the situation from getting worse.
Then work toward increasing your payment over time.
Step 6: Make Payments Earlier or More Frequently
Some people choose to make two or more payments during a billing cycle instead of making one payment near the due date.
This can help in certain situations because credit-card interest may be calculated using daily balances or an average daily balance, depending on the issuer and account terms.
For example, instead of paying:
$400 once near the end of the month
you could potentially pay:
$200 after receiving your first paycheck
and:
$200 after your second paycheck.
The exact interest impact depends on your card's calculation method.
Multiple payments may also make budgeting easier because you are matching payments with your income schedule.
However, don't assume that simply making more payments automatically produces a dramatic interest reduction.
The biggest factor is generally how much total debt you pay down.
Step 7: Consider a Balance Transfer
A balance transfer involves moving eligible debt from one credit card to another card that offers a lower promotional interest rate.
Some balance-transfer cards offer introductory periods with a promotional APR.
For example, a hypothetical offer might provide:
0% promotional APR for 15 months
That can be valuable if you have a realistic plan to repay the balance before the promotional period ends.
But balance transfers are not free money.
There may be:
-
Balance-transfer fees
-
Annual fees
-
Eligibility requirements
-
Credit limits
-
Promotional-period restrictions
-
Higher APR after the promotional period
Always read the terms carefully.
When Can a Balance Transfer Make Sense?
A balance transfer may be worth considering when:
-
Your existing APR is high.
-
You qualify for a significantly lower promotional rate.
-
The transfer fee is reasonable.
-
You have stable income.
-
You have a clear payoff plan.
-
You will avoid adding new debt.
-
You can repay a substantial portion before the promotional period ends.
For example, transferring $5,000 to a promotional account can be useful if you can realistically pay the balance down during the promotional period.
But transferring the balance and then continuing to spend on the original cards can make the problem worse.
Balance Transfer Example
Imagine:
Existing debt: $6,000
Existing APR:
25%
Suppose a balance-transfer offer has a promotional 0% APR period, but charges a transfer fee.
If you transfer the entire balance, the fee increases your new balance.
For example, a hypothetical 3% transfer fee would be:
$6,000 × 3% = $180
So the transferred balance would become approximately:
$6,180
before considering other terms.
If you can pay off the balance during the promotional period, the transfer could still save substantial interest.
But if you cannot repay it before the promotional period ends, you need to understand what rate will apply afterward.
Step 8: Ask Your Credit Card Issuer for a Lower APR
Many consumers never ask their credit-card issuer whether a lower interest rate is available.
You can contact the issuer and ask whether they can reduce your APR.
You might say:
"I've been making my payments on time and I'm trying to pay down my balance. Are there any options available to reduce my interest rate?"
The issuer may or may not agree.
Your chances can depend on factors such as:
-
Payment history
-
Account history
-
Credit profile
-
Current market conditions
-
Issuer policies
-
Your overall relationship with the institution
You can also ask whether the issuer offers:
-
Temporary hardship programs
-
Reduced-rate programs
-
Promotional offers
-
Payment assistance
Never assume approval is guaranteed.
Step 9: Look for a Lower-Interest Consolidation Option
Debt consolidation means combining multiple debts into one payment.
One potential approach is a personal loan with an interest rate lower than your credit cards.
For example:
You have:
-
Card A: 25%
-
Card B: 27%
-
Card C: 23%
A consolidation loan might have a lower interest rate, depending on your creditworthiness and market conditions.
This could simplify your finances.
Instead of making three credit-card payments, you may have one loan payment.
However, consolidation is not automatically better.
Consider:
-
Loan interest rate
-
Origination fees
-
Loan term
-
Total repayment cost
-
Monthly payment
-
Whether the credit cards will be used again
A lower monthly payment does not necessarily mean a lower total cost if the loan lasts much longer.
Step 10: Create a Debt-Focused Budget
A budget gives every unit of income a job.
You can use a traditional monthly budget or a zero-based budgeting approach.
A simplified example:
Monthly income
$4,000
Essential expenses
-
Housing: $1,300
-
Utilities: $250
-
Food: $500
-
Transportation: $300
-
Insurance: $200
-
Other essentials: $250
Total essentials:
$2,800
Remaining:
$1,200
You might allocate part of that amount to:
-
Minimum debt payments
-
Emergency savings
-
Discretionary spending
-
Additional debt repayment
The exact numbers will depend entirely on your circumstances.
The purpose is to make your debt payment an intentional budget category rather than whatever money happens to remain at the end of the month.
Step 11: Cut Expenses Temporarily
You don't have to eliminate every enjoyable activity.
Instead, look for expenses that provide relatively little value compared with their cost.
Potential areas include:
-
Unused subscriptions
-
Frequent food delivery
-
Excessive dining out
-
Impulse shopping
-
Expensive entertainment
-
Unused memberships
-
Frequent rideshare use
-
Luxury purchases
For example, suppose you reduce discretionary spending by:
$250 per month
and redirect that money toward debt.
That's:
$3,000 per year
before considering the effect of interest savings.
A temporary reduction in spending can accelerate debt repayment without requiring a permanent lifestyle change.
Step 12: Increase Your Income
Reducing expenses is only one side of the equation.
Increasing income can be equally powerful.
Potential options include:
-
Freelancing
-
Consulting
-
Part-time work
-
Tutoring
-
Selling unused items
-
Online services
-
Weekend work
-
Overtime where available
-
Monetizing an existing skill
-
Starting a small side business
Suppose you earn an additional:
$400 per month
and send most of it toward high-interest debt.
That's:
$4,800 per year
in additional payments.
Even a temporary increase in income can make a meaningful difference.
Use Windfalls Strategically
Sometimes you receive money outside your normal salary or income.
Examples include:
-
Work bonuses
-
Tax refunds
-
Gifts
-
Commissions
-
Sale proceeds
-
Unexpected income
You don't necessarily have to send 100% of every windfall toward debt.
A balanced approach may be more sustainable.
For example:
-
70% toward debt
-
20% toward savings
-
10% for yourself
The percentages are only an example.
The important idea is to use unexpected money intentionally instead of allowing it to disappear through unplanned spending.
Step 13: Build a Small Emergency Fund
One common mistake is putting every available dollar toward debt while having no emergency savings.
Then an unexpected:
-
Car repair
-
Medical bill
-
Appliance replacement
-
Travel requirement
-
Job interruption
forces you to use the credit card again.
That can create a cycle:
Pay off card → emergency happens → use card → debt returns
For this reason, consider keeping some emergency savings while paying down debt.
The appropriate amount depends on your income stability and expenses.
Someone with highly stable income may have different needs from someone whose income changes significantly each month.
Should You Save or Pay Debt First?
There isn't one universal answer.
If your credit card APR is very high, paying down the balance can provide a strong financial benefit.
But having no emergency cash at all can expose you to the risk of taking on new debt.
A practical approach can be:
-
Maintain a small emergency reserve.
-
Make all required debt payments.
-
Aggressively pay high-interest debt.
-
Gradually increase emergency savings as debt decreases.
Once high-interest debt is eliminated, you can redirect the former debt payments toward savings and investing.
Step 14: Avoid Cash Advances
Credit-card cash advances can be expensive.
Depending on the card's terms, cash advances may involve:
-
A cash-advance fee
-
A separate APR
-
No standard purchase grace period
-
Interest beginning immediately
For these reasons, using a credit card to withdraw cash can be significantly more expensive than using the card for an ordinary purchase.
If you need emergency cash, compare available alternatives carefully rather than automatically using a credit-card cash advance.
Step 15: Protect Your Credit While Paying Debt
Paying down credit cards can help improve your financial situation, but you should also pay attention to your credit profile.
Important factors can include:
-
Payment history
-
Credit utilization
-
Length of credit history
-
New credit applications
-
Types of credit accounts
One important rule:
Avoid missing required payments.
Even if you are aggressively paying one card, continue making at least the required payment on your other accounts unless a formal arrangement says otherwise.
What Is Credit Utilization?
Credit utilization generally refers to how much of your available revolving credit you are using.
For example:
Credit limit:
$10,000
Balance:
$4,000
Utilization:
40%
If the balance falls to:
$2,000
utilization becomes:
20%
Lower utilization is generally viewed more favorably by many credit-scoring models, although scoring systems differ.
The often-repeated "below 30%" guideline is not a universal magic threshold.
The most important long-term goal is to avoid relying heavily on revolving debt.
Don't Close Every Card Automatically
After paying off a card, some people immediately close it.
That can sometimes be appropriate, especially if the account has expensive fees or creates spending problems.
But closing a credit-card account can also affect your available revolving credit and potentially your credit profile.
Consider:
-
Annual fee
-
Age of account
-
Credit limit
-
Spending behavior
-
Credit goals
-
Whether you can keep the account open without using it irresponsibly
There is no universal rule that everyone should keep every paid-off card open or close every card.
Step 16: Use a Debt Payoff Tracker
Debt payoff can feel abstract when you only look at monthly statements.
Create a visual tracker.
For example:
Starting debt: $10,000

████████████████████ 100%

Current debt: $7,500

███████████████      75%

Current debt: $5,000

██████████           50%

Current debt: $2,500

█████                25%

Debt-free: $0

                     0%
You can also track:
-
Total debt paid
-
Interest avoided
-
Number of accounts eliminated
-
Monthly payment
-
Debt-free target date
Visible progress can help maintain motivation.
Psychological Strategies for Paying Off Debt
Debt is not only a mathematical problem.
It can affect:
-
Stress
-
Sleep
-
Confidence
-
Relationships
-
Mental focus
-
Future planning
This is why psychology matters.
Focus on Progress, Not Perfection
You might not be able to pay $1,000 extra every month.
That's okay.
Maybe you can pay:
$100 extra.
Then next month:
$150.
Then:
$200.
Progress is more important than creating an unrealistic plan.
Celebrate Milestones
Debt repayment can take time.
Celebrate meaningful milestones without creating new debt.
For example:
-
First $500 paid
-
First account eliminated
-
25% debt reduction
-
Halfway point
-
Final card paid off
Celebrating doesn't have to mean spending money.
You could:
-
Have a homemade dinner
-
Take a free walk
-
Watch a favorite movie
-
Spend time with friends
-
Take a day off from financial tracking
The goal is to reinforce positive behavior.
Remove Temptation
If online shopping is causing debt, make spending harder.
You can:
-
Remove saved payment methods
-
Unsubscribe from promotional emails
-
Delete shopping apps
-
Disable shopping notifications
-
Create a 24-hour waiting rule
-
Avoid browsing stores when bored
Small environmental changes can reduce impulse purchases.
Use the 24-Hour Rule
Before making a non-essential purchase, wait 24 hours.
For expensive purchases, consider waiting even longer.
Ask:
-
Do I actually need this?
-
Can I pay for it without borrowing?
-
Will I still want it tomorrow?
-
Is this purchase delaying my debt-free goal?
This simple pause can prevent many impulse purchases.
What If Your Debt Is Too Large to Manage?
Sometimes budgeting and extra payments aren't enough.
If you are struggling to make minimum payments, don't simply ignore the problem.
Consider contacting your creditors before the account becomes seriously delinquent.
You may be able to discuss:
-
Hardship programs
-
Modified payment arrangements
-
Reduced interest options
-
Due-date changes
-
Other assistance programs
Availability depends on the lender and your circumstances.
Consider Nonprofit Credit Counseling
A reputable credit counselor can review your financial situation and help you understand possible repayment options.
Depending on the organization and your circumstances, counseling may cover:
-
Budgeting
-
Debt repayment
-
Credit education
-
Debt management plans
A debt management plan is different from simply paying your cards yourself.
In some cases, a counseling agency may negotiate terms with creditors and consolidate eligible payments into one monthly payment.
Always research the organization carefully and understand all fees and terms before enrolling.
Debt Management vs Debt Settlement
These terms are sometimes confused.
Debt Management
A debt management plan generally involves working with a counseling organization to create a structured repayment plan.
You typically repay the debt rather than asking creditors to forgive a portion of it.
Debt Settlement
Debt settlement generally involves attempting to negotiate with creditors to accept less than the full amount owed.
This can involve significant risks.
Potential consequences can include:
-
Fees
-
Credit damage
-
Collection activity
-
Lawsuits in some circumstances
-
Tax consequences depending on jurisdiction and circumstances
-
No guarantee that negotiations will succeed
Be extremely cautious with companies that make unrealistic promises.
Avoid Debt Relief Scams
Be skeptical if a company:
-
Guarantees it can eliminate your debt
-
Demands large upfront fees
-
Tells you to stop communicating with creditors without clearly explaining consequences
-
Tells you to stop making payments without a carefully explained plan
-
Promises a specific credit-score increase
-
Claims government programs will erase your debt immediately
Always research a debt-relief company before providing personal or financial information.
If you are unsure, consider speaking with a reputable nonprofit credit counselor or qualified financial professional.
Step 17: Create a Debt-Free Date
A specific target can make your plan more concrete.
Instead of saying:
"I want to pay off my credit cards someday."
Set a target such as:
"I want to eliminate my credit-card balances within 30 months."
Your target should be realistic.
It depends on:
-
Total debt
-
APR
-
Monthly payment
-
Income
-
Expenses
-
Unexpected costs
You can then work backward.
For example:
Total debt = $9,000
If you want to eliminate it in roughly 24 months, you would need an average principal reduction of around:
$375 per month
before considering interest and other charges.
Because interest is involved, the actual required payment would generally need to be higher.
The point is to turn a vague goal into a measurable target.
A Practical 12-Step Credit Card Debt Payoff Plan
Here is a simple roadmap you can follow.
Step 1: Stop unnecessary new charges
Stop using credit cards to fund spending you cannot repay.
Step 2: List every debt
Write down balances, APRs, minimums, and due dates.
Step 3: Calculate your total debt
Know the exact number.
Step 4: Build a realistic budget
Determine how much you can safely allocate to debt.
Step 5: Keep minimum payments current
Avoid late payments wherever possible.
Step 6: Choose snowball or avalanche
Pick the method that fits your personality and financial goal.
Step 7: Make the extra payment
Direct all additional debt money toward your chosen target.
Step 8: Reduce expenses
Temporarily cut unnecessary spending.
Step 9: Increase income
Use additional earnings to accelerate the plan.
Step 10: Explore lower-interest options
Consider issuer negotiations, balance transfers, or consolidation where appropriate.
Step 11: Track progress
Update your balances every month.
Step 12: Prevent new debt
Once the cards are paid off, change the habits that created the debt.
Real-Life Example: Paying Off $8,000 in Credit Card Debt
Imagine someone has:
Total credit-card debt: $8,000
Average APR:
22%
They currently make minimum payments.
Instead, they create a plan to pay:
$500 per month
while stopping new purchases.
The exact payoff time and interest cost would depend on the individual cards and issuer calculations.
But compared with making only minimum payments, consistently paying $500 can substantially accelerate repayment.
Now imagine they find another:
$200 per month
by cutting expenses and earning additional income.
Their payment becomes:
$700 per month
That additional $200 can significantly reduce the time the debt remains outstanding.
The lesson isn't that everyone must pay $700.
The lesson is:
Increasing the amount you consistently send toward high-interest debt can have a powerful effect over time.
What Happens After You Pay Off a Credit Card?
Paying off your final balance is a major achievement.
But don't immediately assume the job is finished.
The next step is to redirect the money you were previously using for debt payments.
For example:
Before becoming debt-free:
$700/month → credit cards
After becoming debt-free:
$700/month → savings/investments/financial goals
That $700 payment can now work for you instead of going toward interest.
Build an Emergency Fund After Debt Payoff
Once expensive credit-card debt is gone, strengthen your emergency savings.
The appropriate emergency-fund target depends on:
-
Income stability
-
Household size
-
Fixed expenses
-
Job security
-
Insurance
-
Health and family circumstances
Some people start with a small reserve and eventually work toward several months of essential expenses.
The goal is simple:
Make unexpected expenses less likely to push you back into credit-card debt.
Start Saving for Long-Term Goals
After high-interest debt is eliminated and your emergency savings are in place, you can redirect money toward long-term goals.
These might include:
-
Retirement
-
Education
-
Home purchase
-
Business
-
Investment
-
Travel
-
Family goals
The exact order depends on your personal circumstances.
But removing high-interest revolving debt can create significant financial flexibility.
How to Avoid Credit Card Debt in the Future
Paying off debt is only half the battle.
The real victory is not returning to the same cycle.
Consider these habits.
Pay the Statement Balance When Possible
If your card terms provide a grace period for purchases and you pay the statement balance in full by the due date, you may avoid interest on purchases.
Always check your card's specific terms.
Use Credit for Planned Purchases
Don't use credit simply because you have available credit.
Ask whether the purchase already fits your budget.
Keep an Emergency Fund
Savings can reduce the need to borrow when unexpected expenses occur.
Monitor Your Statements
Review statements regularly for:
-
Incorrect charges
-
Subscriptions
-
Fees
-
Fraud
-
Unrecognized transactions
Don't Increase Spending Just Because Your Limit Increased
A higher credit limit does not mean you have more income.
Your spending should be based on your budget, not your available credit.
The Difference Between Being Credit-Rich and Cash-Rich
A credit card can make someone appear financially capable because they have access to a large credit limit.
But available credit is not the same thing as wealth.
For example:
Someone with:
$20,000 available credit
is not necessarily financially stronger than someone with:
$10,000 in savings
if the first person has significant debt and the second person has none.
Focus on:
-
Net worth
-
Savings
-
Cash flow
-
Debt
-
Financial resilience
rather than simply your credit limit.
Common Mistakes When Paying Off Credit Card Debt
Mistake 1: Paying One Card While Ignoring Others
Always make required payments on your other accounts unless you have a formal arrangement that changes those requirements.
Mistake 2: Continuing to Spend
If you pay $500 but add $600 in new purchases, your balance can still rise.
Mistake 3: Choosing an Unrealistic Payment
Don't promise yourself you'll pay $1,500 every month if your budget cannot support it.
Mistake 4: Ignoring Interest Rates
If you are using the avalanche method, APR is critical.
Mistake 5: Ignoring Fees
Balance transfers, loans, annual fees, and other charges can change the economics of a strategy.
Mistake 6: Emptying All Savings
A zero savings balance can make the next emergency expensive.
Mistake 7: Using One Card to Pay Another Without a Plan
Moving debt around doesn't eliminate it.
Mistake 8: Trusting Debt Relief Promises
Be careful with companies promising instant or guaranteed debt elimination.
Should You Pay Off Credit Cards Before Investing?
This is a common question.
There isn't one universal answer.
However, high-interest credit-card debt is generally expensive.
If you are paying a very high APR on revolving debt, paying it down can provide a predictable financial benefit because you are avoiding future interest charges.
At the same time, employer retirement matches or other important financial priorities may deserve consideration.
A practical framework is:
-
Keep required payments current.
-
Maintain some emergency savings.
-
Capture valuable employer retirement matching opportunities when applicable.
-
Aggressively address expensive high-interest debt.
-
Build long-term investments after your financial foundation becomes stronger.
Your circumstances may justify a different order.
Should You Use a Personal Loan to Pay Off Credit Cards?
A personal loan may be useful if:
-
Its interest rate is substantially lower.
-
Fees are reasonable.
-
You stop accumulating new credit-card debt.
-
The repayment term is manageable.
-
The total cost is lower.
But don't use consolidation as an excuse to continue spending.
A common failure pattern is:
Credit cards paid off → cards reused → personal loan remains → total debt increases
Consolidation works best when it is combined with a change in spending behavior.
How Much Should You Pay Toward Credit Card Debt Each Month?
There is no universal number.
The right payment depends on:
-
Income
-
Essential expenses
-
Debt balance
-
APR
-
Emergency savings
-
Family obligations
-
Financial goals
A useful principle is:
Pay the maximum amount you can sustain without failing to cover essential expenses or repeatedly relying on new debt.
Consistency matters.
Is It Better to Pay Debt Weekly, Biweekly, or Monthly?
The frequency matters less than the total amount and timing.
If your card's interest calculation is based on daily balances, earlier payments can potentially reduce interest compared with waiting until later, all else equal.
Biweekly payments can also help people who receive biweekly paychecks.
For example:
$300 twice per month = $600
If you instead make one $600 payment at the end of the month, the total payment is the same, but the timing differs.
Check your issuer's terms and payment-processing rules.
What If You Have Multiple High-Interest Cards?
This is where the avalanche method can be particularly useful.
Suppose you have:
-
Card A: $2,000 at 18%
-
Card B: $4,000 at 29%
-
Card C: $3,000 at 24%
Under avalanche:
Card B → Card C → Card A
You still make minimum payments on all three.
Your extra money goes toward Card B first because it has the highest APR.
After Card B is paid off, redirect that payment to Card C.
What If the Smallest Balance Has a Very High APR?
This is an excellent situation for combining the two methods conceptually.
Suppose:
-
Card A: $500 at 29%
-
Card B: $4,000 at 20%
-
Card C: $6,000 at 18%
The smallest balance is also the highest APR.
Both strategies would target Card A first.
This is why it is useful to compare both the balance and interest rate before choosing your order.
A Simple Debt Payoff Worksheet
You can create your own worksheet with these fields:
TOTAL CREDIT CARD DEBT:
________________________

MONTHLY INCOME:
________________________

ESSENTIAL EXPENSES:
________________________

TOTAL MINIMUM PAYMENTS:
________________________

EXTRA DEBT PAYMENT:
________________________

HIGHEST APR:
________________________

SMALLEST BALANCE:
________________________

PAYOFF METHOD:
Snowball / Avalanche

TARGET DEBT:
________________________

TARGET PAYOFF DATE:
________________________
Update it once or twice per month.
Don't obsess over your balance every hour.
A consistent monthly review is usually enough to track meaningful progress.
Your 30-Day Credit Card Debt Challenge
If you want to start immediately, use the following 30-day plan.
Days 1–3: Get Organized
List every debt.
Find:
-
Balance
-
APR
-
Minimum
-
Due date
Calculate total debt.
Days 4–7: Review Spending
Look at your last few weeks of transactions.
Identify unnecessary spending.
Week 2: Create Your Budget
Decide how much extra you can send toward debt.
Choose snowball or avalanche.
Week 3: Reduce Expenses
Cancel or reduce unnecessary expenses.
Find at least one way to increase income if possible.
Week 4: Make Your First Extra Payment
Send your planned extra payment toward the target debt.
Then schedule the next payment.
The objective isn't to completely eliminate your debt in 30 days.
The objective is to establish a system that continues working after the first month.
The Most Important Rule: Don't Give Up
Debt repayment can be frustrating.
You may have months when:
-
Expenses unexpectedly increase
-
Income falls
-
An emergency happens
-
Your payment is smaller than planned
One difficult month does not erase your progress.
Instead of abandoning the plan, adjust it.
For example:
Original payment: $600
Unexpected expense:
$300
Adjusted payment:
$300
That's still progress.
The goal is not perfection.
The goal is to keep moving in the right direction.
Final Summary: How to Pay Off Credit Card Debt Faster
If you want to eliminate credit-card debt as efficiently as possible, focus on the fundamentals.
1. Stop adding unnecessary debt
Don't continue borrowing while trying to repay.
2. Know exactly what you owe
List balances, APRs, minimum payments, and due dates.
3. Create a realistic budget
Know how much money you can actually direct toward debt.
4. Choose a repayment strategy
Use:
Debt Snowball for psychological momentum.
or:
Debt Avalanche for interest efficiency.
5. Pay more than the minimum
Even relatively small additional payments can add up.
6. Consider payment timing
Earlier or multiple payments can sometimes reduce interest based on how your issuer calculates balances.
7. Explore lower-interest options
Consider balance transfers, issuer hardship programs, or consolidation when the numbers make sense.
8. Negotiate your APR
Ask your card issuer whether a lower rate or assistance program is available.
9. Reduce unnecessary expenses
Temporarily redirect discretionary spending toward your debt.
10. Increase income
Use additional income to accelerate repayment.
11. Keep an emergency reserve
Avoid creating a situation where the next unexpected expense forces you to borrow again.
12. Protect your credit
Make required payments on time and monitor your accounts.
13. Avoid debt-relief scams
Research companies carefully and understand all costs and risks.
14. Build better habits after becoming debt-free
Use the money that once went toward credit-card payments to build savings and achieve long-term financial goals.
Final Thoughts
Credit card debt can feel overwhelming, especially when high interest rates and multiple balances make your progress seem slow.
But debt is not something you have to approach randomly.
You can turn it into a structured process.
First, understand exactly how much you owe.
Then stop adding unnecessary debt.
Create a realistic budget.
Choose a repayment strategy.
Pay more than the minimum whenever your budget allows.
Look for opportunities to lower your interest rate.
Increase your income if possible.
Track your progress.
And most importantly, build financial habits that prevent the same debt cycle from returning.
There is no single strategy that works perfectly for everyone. A person with stable income, a large emergency fund, and excellent credit may have very different options from someone struggling to make minimum payments.
What matters is choosing a strategy that fits your actual financial situation.
Debt freedom is not achieved by one perfect decision. It is achieved through many consistent decisions over time.
Every payment reduces your balance.
Every unnecessary expense you avoid creates additional room in your budget.
Every extra dollar directed toward high-interest debt can reduce the amount you may otherwise pay in interest.
And every month you stay consistent brings you closer to financial freedom.
🚀 Start Your Debt Payoff Plan Today
Don't wait for the "perfect" month to begin.
Start with three simple actions today:
1. Write down your total credit-card debt.
2. Find the APR and minimum payment for each card.
3. Decide how much extra you can realistically pay every month.
Then choose your strategy:
Snowball → smallest balance first
Avalanche → highest APR first
Once you have a plan, consistency becomes the most important part.
Your goal isn't simply to have a lower credit-card balance.
Your ultimate goal is to build a financial system where your income supports your lifestyle, emergencies don't automatically become debt, and your money can eventually be directed toward savings, investments, and the future you want.
Start today. Stay consistent. Take control of your debt one payment at a time.
Frequently Asked Questions About Paying Off Credit Card Debt
What is the fastest way to pay off credit card debt?
For multiple high-interest cards, the debt avalanche method is generally the most interest-efficient approach: make required minimum payments on all accounts and direct extra money toward the card with the highest APR.
However, the fastest strategy in real life is the one you can consistently follow.
Should I use the debt snowball or avalanche method?
Use the snowball method if quick psychological wins help you stay motivated.
Use the avalanche method if minimizing interest is your primary goal.
Both can be effective.
Is it bad to make only the minimum payment?
Making the required minimum payment may keep the account current, but it can result in a much longer repayment period and more interest compared with paying additional amounts.
Can I negotiate my credit-card interest rate?
You can ask your card issuer whether a lower APR or hardship option is available. Approval is not guaranteed.
Are balance transfers worth it?
They can be useful when the promotional rate, transfer fee, repayment timeline, and other terms make financial sense. Always read the full offer terms.
Should I stop using my credit cards?
If continued use is causing your balance to increase, temporarily stopping new purchases can make debt repayment much easier. The right approach depends on your situation and spending habits.
Can making payments twice a month help?
It can potentially reduce interest in some situations because credit-card interest may depend on daily balances or average daily balances. It can also make budgeting easier. However, the total amount you pay toward the balance remains a major factor.
Should I close a credit card after paying it off?
Not necessarily. Closing an account can affect your available credit and potentially your credit profile. Consider the card's fees, age, credit limit, and whether keeping it open could encourage overspending.
What if I can't afford my minimum payments?
Contact your creditors as soon as possible and ask about available hardship or payment-assistance options. You may also consider speaking with a reputable credit counselor.
Is debt consolidation a good idea?
It can be useful if it meaningfully lowers your borrowing cost and you have a plan to avoid rebuilding credit-card debt. Compare the total cost, fees, interest rate, and repayment term before making a decision.
How long does it take to become debt-free?
There is no universal timeline. It depends on your total balance, APRs, monthly payments, new charges, income, and expenses. Increasing your payment and reducing new borrowing generally speeds up the process.
What should I do after paying off my credit cards?
Consider redirecting your former debt payments toward emergency savings, retirement, investments, or other long-term financial goals.
The goal isn't simply to become debt-free.
The goal is to stay debt-free and build financial security.
Your email address will not be published. Comments are moderated.
0 Comments on This Post
Leave a Reply
Comments (0)
Spread the Word!
Join Our Developer Community!
Get weekly coding tips, tool updates, and exclusive tutorials straight to your inbox.
Request a Tool
×